History
Looking at the history of any industry can sometimes get a bit lost, but with insurance it is really important, simply because today’s market still basically runs on the same principles on which it was founded.
Most people will have heard about Lloyd’s of London, even if they don’t know much about how it operates or what it is made-up of.
After the great fire of London in 1666, much of the City of London was destroyed, and with it most of the commercial activity that went on there. As part of the rebuilding process, many traders and men of commerce would meet in one of the many coffee shops that existed in the City of London after the fire, to begin the process of rebuilding commerce.
One of these coffee shops was owned by a man called Edward Lloyd, and his coffee shop soon became the go-to meeting place for shipowners, traders and merchants. Initially they met really to discuss intelligence about what was going on around the world concerning their various shipping routes, but this soon developed into a very basic type of insurance.
Men of commerce began to offer financial protection against losses that the shipowners might incur as a result of damage caused by shipwrecks, bad weather, pirates etc.
This protection was written down in the form of a very basic contract, and signed at the bottom of the page by the businessman, hence the term underwriter.
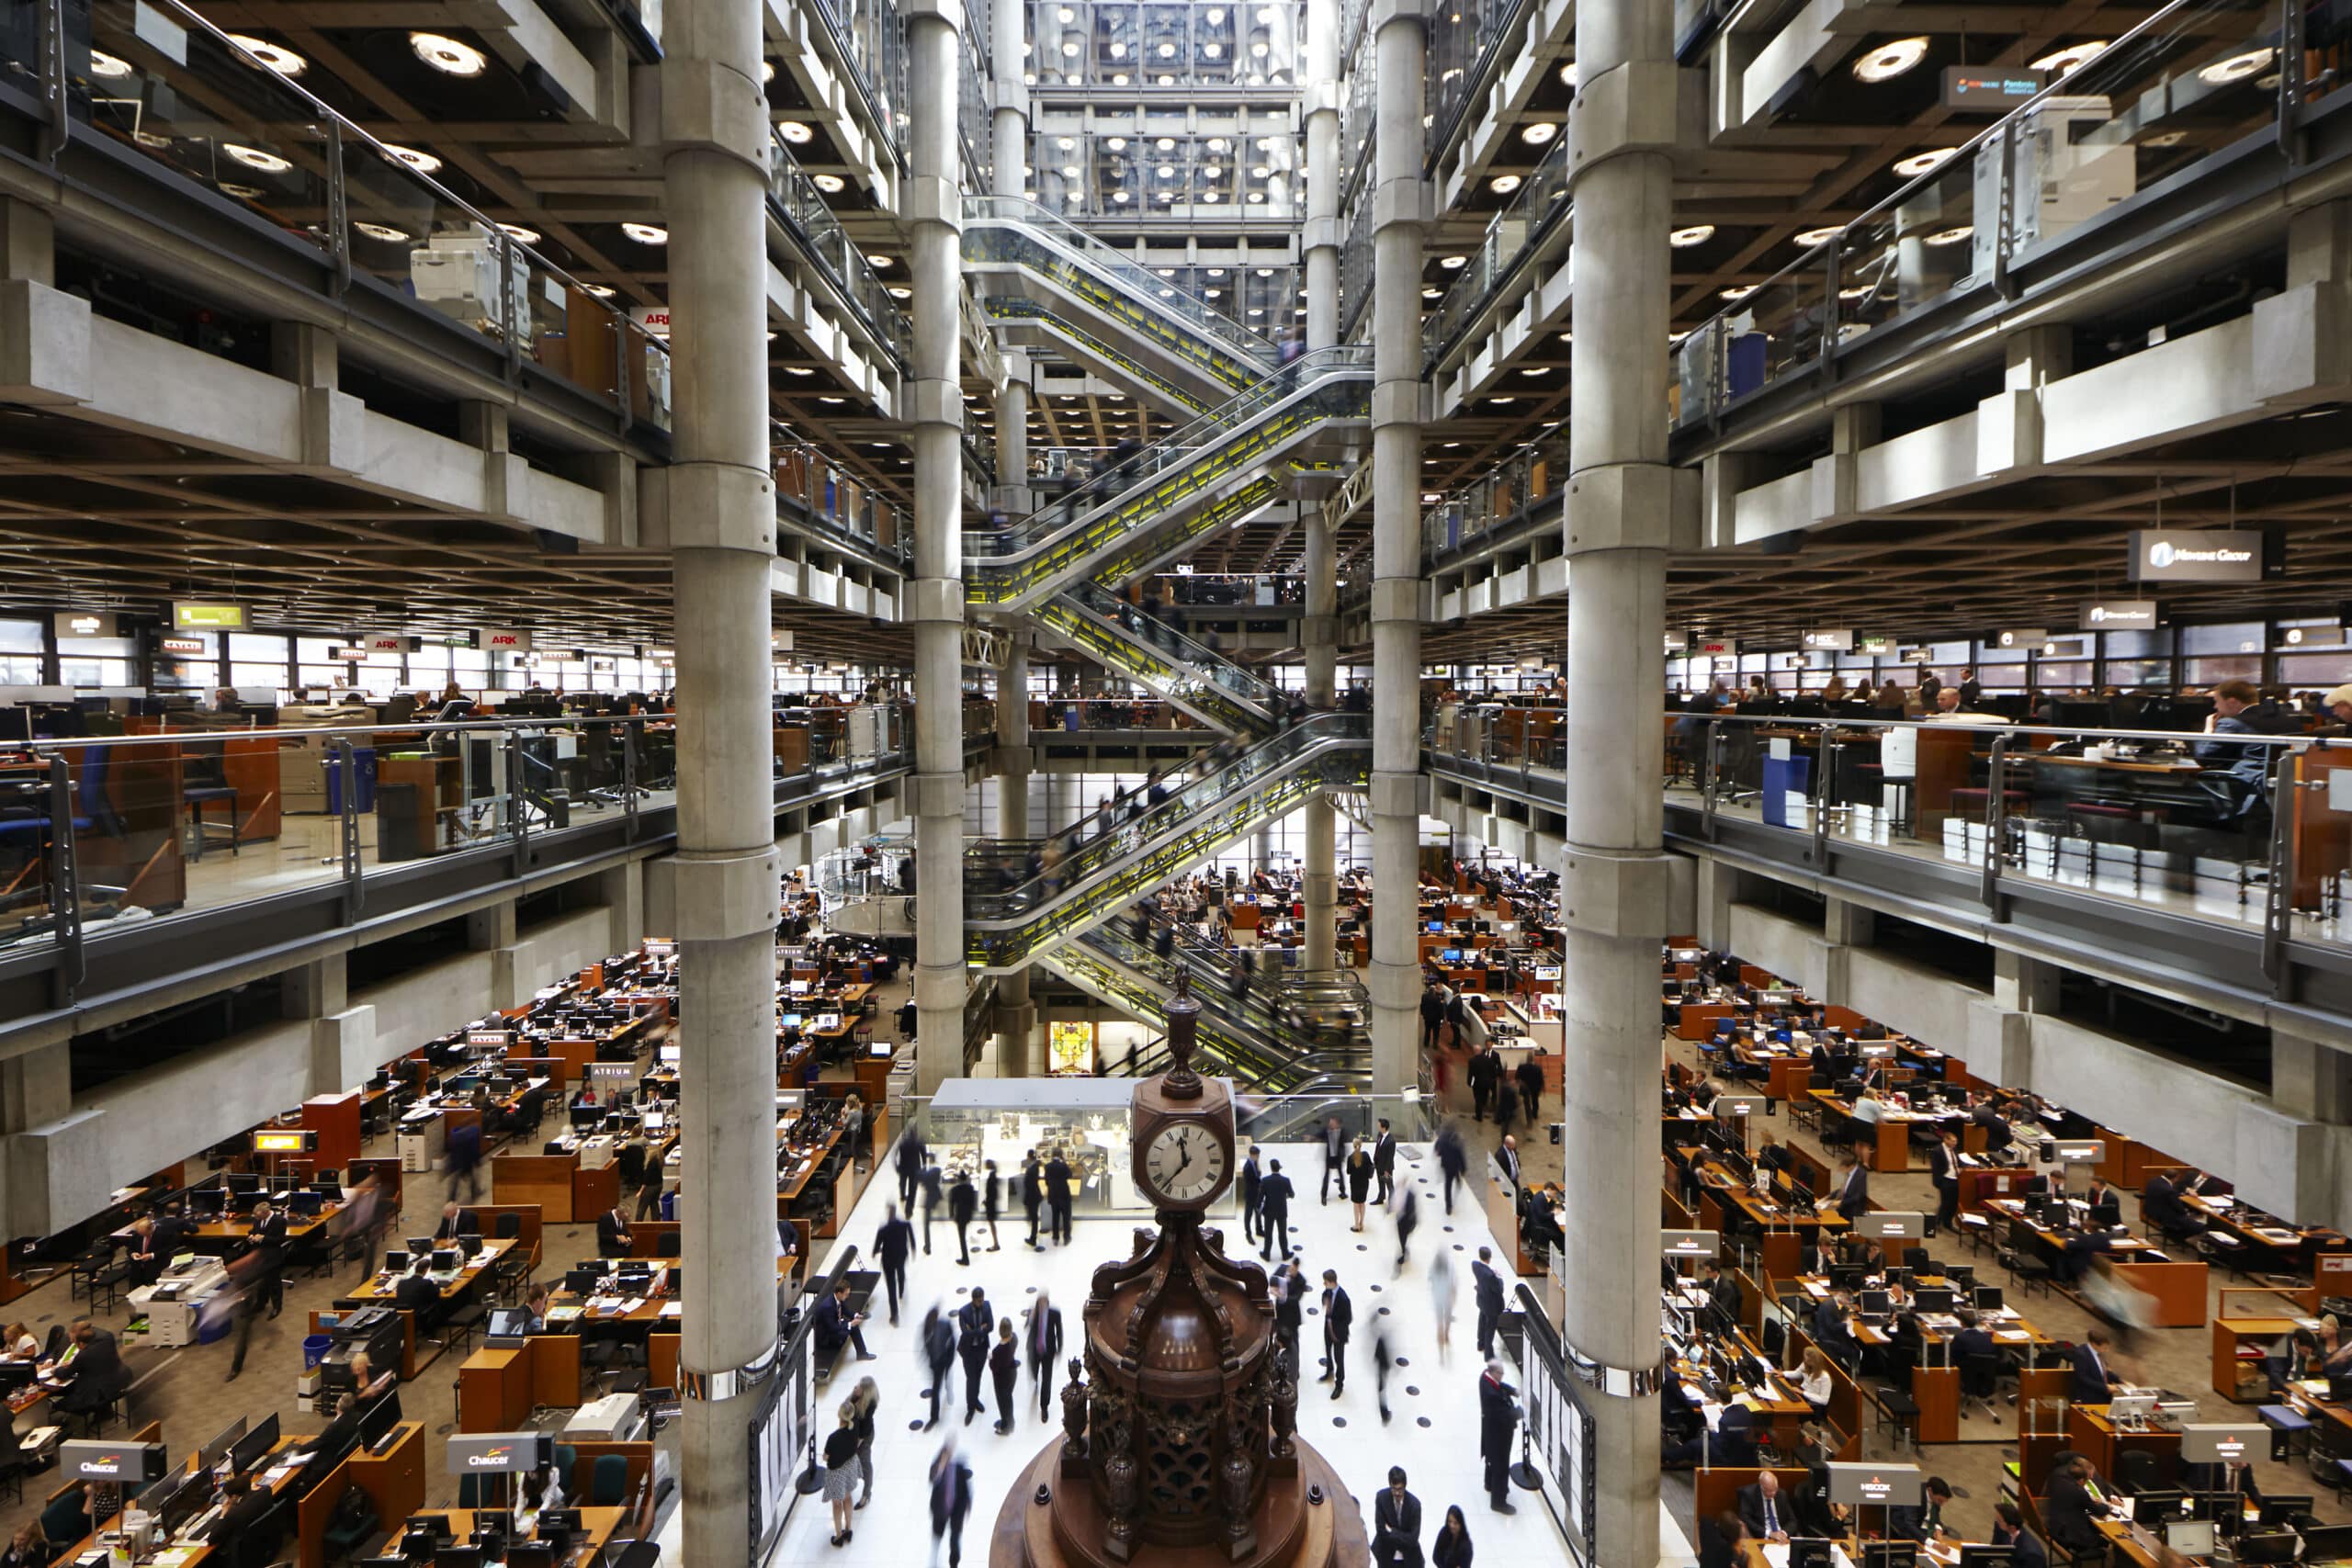
This very simple sketch of how insurance began has the foundations of the current insurance market. The activity at this coffee shop, belonging to Edward Lloyd, soon outgrew the premises, and over time has grown into a huge marketplace with its own dedicated building, insuring virtually everything you can think of around the world and beyond.
The other important thing to realise about this is that current day Lloyd’s is not one company, nor has it ever been. It is essentially a collective name for hundreds of different companies, known as syndicates, who work under this umbrella of Lloyd’s, both as individual companies but also work together to cover particular risks.
On this site, there are numerous references to the term insurance companies, and for the sake of simplicity the term insurance companies will include Lloyds of London, although it is not actually a company, unless otherwise stated.
Insurance Roles
This is really about understanding the terminology that is used when talking about the various people who are involved in deciding whether or not to insure something, arranging that insurance and processing any claims that may arise under it.
Underwriter
The term underwriter, as referenced above, still refers to the individual who ultimately decides whether to insure a particular risk, how much to charge for it and any terms and conditions or restrictions on the cover provided.
In reality an underwriter will have a team of assistants who will also work on the same principles as above. There are also likely to be a whole string of experts relating to risk management, risk modelling and all the various activities that go on behind making a decision as to the viability and potential liability of a potential risk.
Broker
An insurance broker is the individual, although normally part of a firm of brokers, who act as the middle man between insurance companies and consumers. Consumers can either be individual men and women or huge corporations, small businesses and blue chip companies.
The role of an insurance broker is to act in the best interest of their client, who is the consumer. This means they are obligated to try and find the best level of cover for their client, in terms of the most appropriate insurance for that particular individual or business, at the most reasonable cost.
They are not obligated to find the cheapest insurance, simply the insurance that provides the best level of cover for their client.
The insurance broker acts as the agent of the consumer, always, but is actually paid by the underwriter or insurance company by way of a commission. This is a slight quirk of the law of agency, but ensures that the insurance broker always acts in the best interests of the client.
Agent
The word agent is used a lot in insurance circles and can have quite different meanings, depending upon their role.
1. Traditionally, some insurance companies used agents effectively as door to door salesman, often selling life assurance, sometimes together with other types of insurance such as home or auto insurance.
This is often how people think of an agent, as a representative of a company, who takes a commission on anything they sell. This still happens in certain countries, but is less common nowadays than it was number of years ago.
2. Certain types of businesses can also act as an agent for an insurance company. Most commonly they tend to be businesses such as banks, mortgage companies or travel companies who sell a particular type of insurance on behalf of a major insurance company.
Morally, they should always declare that they are an agent of the company, and in some jurisdictions, they have a legal obligation to do so. The business can also act as an agent for more than one company and have the freedom to sell whichever policy they want to, to a potential consumer.
3. A lot of countries have quite strict legal and ethical codes of how insurance brokers need to act. Where this is the case, many companies set themselves up as so-called agencies, so they can act as the role of an insurance broker without what they consider any legal or ethical restraints.
These companies often act perfectly legally, but care needs to be taken if they are being used as to how they see their role in the purchasing of insurance for a consumer.
4. The other term where agent is used often applies to what is known as a Lloyd’s agent. This can be slightly confusing as there can be very different meanings ascribed to it.
5. One meaning refers to numerous individuals or companies scattered around the world who provide market intelligence to the Lloyds insurance community, a continuance in many ways of the original function of the coffeehouse of Edward Lloyd in the1600s.
6. The other function of a Lloyds agent, which is completely different, is that of a sort of management company of a specific syndicate who make up the Lloyd’s market. This type of agency oversees and manages the corporate and financial responsibility of the syndicate itself, and also is ultimately responsible for the underwriting policy that the syndicate pursues.
Legal Principles of an Insurance Policy
It is always worth remembering that an insurance policy is first and foremost a legally binding contract between two parties, with very specific terms and conditions applying to both parties. Often an insurance company will be quite flexible in their approach to settling claims, where it is appropriate, but that is not always the case – some insurance companies will see things in a purely legal context.
As with anything legal. there can often be differing interpretations of what things mean, within the context of an insurance policy. There are however certain principles laid down in the Marine Insurance Act of 1906, which forms the basis of insurance law in the UK, and throughout most of the world.
Two of the most important principles are worth flagging up.
Indemnity – this principle means that in the event of a claim, the the person who is insured is placed in the same position as they were before the loss happened. This is meant to ensure that no-one profits from a loss.
An example would be of a person who drove a ten year old Honda Civic, which was stolen and never recovered. Assuming its a legitimate claim, the insurance company would be under an obligation to provide the insured with another ten year old Honda Civic. Realistically they would offer a cash alternative, which can often lead to claims disputes.
Insurable Interest – this principle generally means that the person taking out the insurance needs to have needs to have some type of interest that would be harmed in the event of loss or damage to whatever is being insured.
An example would be property insurance, where a homeowner would have an interest in insuring their property against a number of perils, as would a mortgage company or bank.
The principle of insurable interest is essentially to try and stop people gambling with other people misfortunes. There are however numerous situations where someone does have an insurable interest in taking out a policy, the legitimacy of which usually be decided by an insurance company.
Utmost good faith – The principle of utmost good faith is a key element of all insurance policies. In very simple terms it means that whoever is taking out the insurance policy, whether it is an individual or a corporation or business, they have an obligation to disclose to the insurance company all information that could potentially be deemed relevant.
This allows the insurance company to make a realistic assessment as to the nature of the risk, whether or not they wish to insure it, and if so at what cost and on what terms and conditions.
Most of the information that the insurance company requires will be in the form of question that they ask the potential policy holder, but it is still an obligation on the person taking out the insurance to disclose all relevant information whether asked for or not.
Glossary
Below is a link to the Lloyd’s website glossary, containing details of both Lloyd’s terms and wider insurance terms as well